Help around the home is just a few clicks away
Small Business Planning in India: A Practical Checklist Before You Launch
Plan a small business in India by validating demand, estimating costs, choosing a model, organising compliance and tracking early performance. This guide offers practical steps for making a more informed decision. Adapt the checklist to your own circumstances and verify any legal, financial, health or technical requirements through the relevant official source or qualified professional.
Validate the problem before investing
Describe the customer problem your business will solve and identify who experiences it most often. Speak to potential customers, compare existing alternatives and test whether people will pay for your proposed solution. Likes and positive comments are not the same as buying intent. A small pilot, pre-order or limited service launch can reveal useful information before you commit to a long lease, large inventory or expensive technology.
Build a realistic cash-flow plan

List one-time setup costs, fixed monthly expenses, variable costs, taxes, marketing, salaries, refunds and a contingency reserve. Estimate revenue using conservative assumptions and calculate how many sales are needed to cover costs. Profit on paper does not always mean enough cash is available to pay suppliers on time. Review the plan monthly and update it with actual numbers rather than treating the first forecast as permanent.
Choose a suitable operating and legal structure

The right business structure depends on ownership, liability, funding plans, administrative effort and tax circumstances. Registration, licences, GST, employment rules and sector-specific obligations vary by activity and location. Verify requirements through official government portals or a qualified professional. Do not assume that a registration or tax number automatically grants every permission needed to operate.
Measure progress with a few key indicators

Track leads, conversion rate, repeat purchases, gross margin, cash balance, delivery time and customer complaints. Choose measures that connect to decisions; a large social following may not translate into sustainable sales. Review customer feedback regularly and make one or two controlled improvements at a time. Protect customer information, document important processes and keep written agreements with partners and suppliers.
Final checklist

Write down your priorities, compare options using the same criteria, confirm important details directly with the relevant provider and keep records of agreements. Revisit the plan when your needs change rather than relying on assumptions or outdated information. The Infinity Company shares practical guides to help readers make more informed decisions.
About this guide: This article is for general informational purposes. Product terms, local rules and individual circumstances may differ; verify important details before acting.
How to Compare Electric Cars in India: Range, Charging, Cost and Ownership
A practical checklist for comparing electric cars in India, including real-world range, charging access, battery warranty, running costs and ownership needs. This guide offers practical steps for making a more informed decision. Adapt the checklist to your own circumstances and verify any legal, financial, health or technical requirements through the relevant official source or qualified professional.
Start with your daily driving pattern
Estimate your normal daily kilometres, weekend trips and longest regular journey before comparing electric cars. Advertised range is measured under test conditions; actual range can vary with speed, air conditioning, temperature, load, terrain and driving style. Choose a vehicle that leaves a practical buffer for your routine rather than relying on the maximum figure in a brochure.
Check charging access before buying

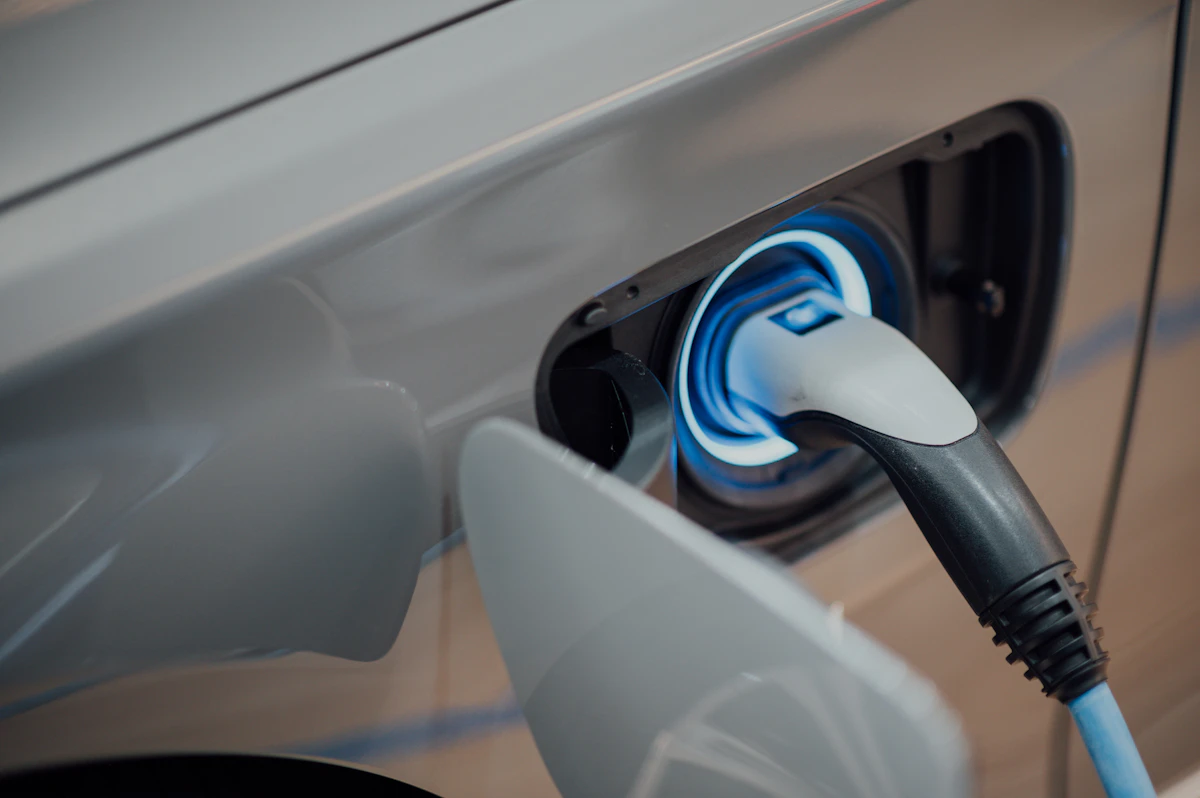
Home charging can be convenient when parking and electrical installation allow it. Apartment residents should confirm permissions, wiring capacity, metering and installation costs. For public charging, map stations on the routes you actually use and check connector compatibility, operating hours and payment methods. A charger appearing on a map does not guarantee that it is available or working.
Compare the total cost of ownership
Compare the on-road price, financing, insurance, charging equipment, electricity, servicing, tyres, battery warranty and expected resale value. Fuel savings alone do not establish which car is cheaper; your annual distance, electricity tariff and purchase price matter. Ask for a written quotation and review current incentives or registration rules through official sources before including them in calculations.
Final inspection checklist

Take a test drive in city traffic and at highway speeds where possible. Check visibility, boot space, rear-seat comfort, safety equipment, warranty exclusions, roadside assistance and service access in your area. Ask what battery capacity warranty means and how battery health is assessed. This guide is general information; confirm specifications and terms with the manufacturer and authorised dealer.
Final checklist

Write down your priorities, compare options using the same criteria, confirm important details directly with the relevant provider and keep records of agreements. Revisit the plan when your needs change rather than relying on assumptions or outdated information. The Infinity Company shares practical guides to help readers make more informed decisions.
About this guide: This article is for general informational purposes. Product terms, local rules and individual circumstances may differ; verify important details before acting.
Health Insurance for Senior Citizens in India: Benefits, Costs and Buying Checklist
Finding health insurance for an older parent or senior family member requires more than comparing premiums. Hospital coverage, waiting periods, co-payments, medical disclosures, nearby hospitals and renewal affordability can all affect the value of a policy. This guide explains the main benefits and limitations of senior citizen health insurance in India. Policy terms vary, so verify details in the actual policy wording before making a decision.
Introduction: Why senior citizens may need health cover
As people age, the likelihood of needing medical consultations, diagnostic tests, hospital treatment and ongoing care can increase. Health insurance may help manage eligible expenses, but it does not make every treatment free or guarantee acceptance of every claim. Senior citizen policies differ in eligibility, premiums, waiting periods, co-payments, exclusions and limits. The right choice depends on a person’s health history, budget, preferred hospitals and ability to pay expenses that remain outside the policy. Review the full policy wording and insurer’s Customer Information Sheet before purchasing.
1. What is senior citizen health insurance?
Senior citizen health insurance is a medical insurance product designed for older applicants or a plan that allows older people to enrol, subject to its terms. Some policies are specifically marketed to seniors; others accept a wider age range and may offer broader features. Do not judge a plan by its name alone. Check entry-age limits, medical screening requirements, renewal conditions, covered hospitalisation expenses, sub-limits and exclusions. Ask the insurer to confirm eligibility in writing if the applicant has multiple medical conditions or a complex treatment history.
2. Main benefit: help with eligible hospital bills

Depending on the policy, health insurance may cover eligible inpatient hospitalisation, surgery, room charges, nursing, prescribed medicines and diagnostic services linked to a covered admission. Some plans include specified day-care procedures that do not require a full 24-hour stay. Limits can apply to room category, particular procedures or the total sum insured. Non-medical items and expenses not meeting policy conditions may not be payable. Compare the actual coverage table and exclusions instead of assuming that every bill from a hospital will be covered.
3. Helps reduce pressure on retirement savings

Unexpected hospital costs can place pressure on pensions, savings and family budgets. A suitable policy may pay eligible claims and reduce the amount that must be withdrawn from savings. This can help reserve money for housing, daily living, medicines and other responsibilities. However, premiums themselves must remain affordable, and a policy with high co-payments or strict limits may still leave a significant bill. Consider both the annual premium and the potential out-of-pocket amount during a serious admission when comparing plans.
4. Pre-existing diseases and honest disclosure
Conditions such as diabetes, hypertension, heart disease or respiratory illness may be relevant to underwriting and claims. Tell the insurer accurately about diagnosed conditions, past procedures, current medication, investigations and other information requested in the proposal. Do not hide a condition to obtain a lower premium. Pre-existing disease waiting periods and coverage rules vary by product and applicable regulation. Ask how the policy defines a pre-existing disease, when related claims may become eligible, and whether any permanent exclusion or special condition applies.
5. Waiting periods: what they mean
A waiting period is a defined period during which specified benefits or conditions are not covered, or are covered only after stated requirements are met. Policies may have an initial waiting period, condition-specific waiting periods and rules for pre-existing diseases. Accident-related treatment may be handled differently under the wording. Never assume that buying a policy today means all existing conditions are covered tomorrow. Read the exact durations and applicable exceptions, and ask the insurer to explain any condition-specific waiting period in writing before paying the premium.
6. Co-payment and deductibles
A co-payment means the insured person pays a specified share of eligible expenses. A deductible is an amount that must be borne before the insurer starts paying the applicable claim. Some senior-oriented products may include one or both. These features can reduce the premium but increase costs at the time of treatment. For example, if a policy requires the customer to pay a percentage of an eligible bill, that share can become substantial for an expensive admission. Compare the financial effect using realistic hospital-bill examples, not just the premium quote.
7. Sum insured and medical cost planning
The sum insured is the policy’s stated coverage amount, subject to policy terms and any applicable sub-limits. When choosing a level of cover, consider treatment costs in your city, the hospitals you are likely to use, age, medical history, number of covered people and existing insurance. A low sum insured may be used up by one large admission, while a higher amount may come with a premium that strains the budget. Check whether restoration or recharge benefits exist and exactly when they can be used; do not treat them as unlimited cover.
8. Individual policy versus family floater
An individual policy allocates cover to one insured person, while a family floater typically shares one sum insured among the people named in the plan. For older parents, a separate policy can make benefits and costs easier to evaluate, but it is not automatically the best option in every case. Check eligibility, premium, medical underwriting, renewal terms and how a large claim would affect remaining cover. If parents are included in an employer or family plan, confirm whether their cover continues if employment or the main policyholder’s circumstances change.
9. Network hospitals and cashless treatment

A cashless facility may allow the insurer or its administrator to settle approved expenses directly with a network hospital. Approval and payment remain subject to policy conditions, authorisation and the hospital’s billing details. Before buying, search the insurer’s current network for hospitals near the senior’s home and preferred specialists. Network lists can change, so verify directly before planned treatment. Cashless does not mean every charge is covered: non-payable items, co-payments, deductibles and expenses beyond limits may still be payable by the patient.
10. Room rent limits and proportionate deductions

Some policies specify room-category limits or other restrictions that can affect the payable amount. Choosing a room above the allowed category may lead to additional charges and, depending on the wording, related proportionate deductions. Other plans may offer fewer or no room-rent limits but have different premiums or conditions. Read the room eligibility clause carefully and ask the insurer to explain what happens if the preferred room is unavailable. A policy’s headline sum insured alone does not tell you how much of a hospital bill will be approved.
11. Pre- and post-hospitalisation benefits
Some policies cover specified medical expenses incurred for a defined number of days before and after a covered hospitalisation, when they relate to that admission and meet policy rules. These benefits may help with consultations, diagnostic tests or prescribed medicines. The number of days, documentation requirements and eligible expense types vary. Keep original prescriptions, bills, investigation reports, discharge summaries and payment proofs. Do not assume routine outpatient consultations or long-term medicine refills are covered unless the policy explicitly includes those benefits.
12. Day-care procedures and domiciliary treatment

Some treatments can be completed in a hospital or day-care facility without a traditional 24-hour admission. A policy may cover listed or qualifying day-care procedures subject to its definitions. Certain plans may also cover domiciliary treatment or home-based care under specific medical and policy conditions, but this is not universal. Ask for the list of covered procedures, the definition of hospitalisation, any minimum treatment requirements and required approvals. Confirm these points before planned treatment whenever possible.
13. Annual health check-ups and wellness features
Some policies provide preventive health check-ups, wellness services or teleconsultation benefits, but the availability, frequency and limits vary. These features can be useful conveniences, yet they should not outweigh essential hospital cover, reasonable co-payment terms and clear exclusions. Check whether the benefit is cashless, reimbursement-based or limited to specified providers. Do not buy a policy solely for a free check-up if the core cover does not meet the person’s likely medical and financial needs.
14. Premiums and renewal affordability
Premiums can depend on age, location, sum insured, medical history, policy design, co-payment, deductible and other underwriting factors. Premiums may rise at renewal due to age bands, medical inflation, product changes or other permitted factors. Ask for the current premium and understand the insurer’s renewal terms rather than relying on an introductory quote. Check whether you can sustain the premium over time. Letting a policy lapse can affect continuity benefits and waiting-period credit, subject to the applicable rules and product terms.
15. Medical tests and underwriting
An insurer may request medical tests or records before deciding whether to offer cover and on what terms. Requirements vary by age, health disclosures and product. Complete requested tests through the specified process and keep copies of results. If the insurer offers revised terms, exclusions or a different premium, review them carefully before accepting. A policy schedule and written underwriting decision are more reliable than a verbal assurance. Ask how to correct an error in the application or policy documents as soon as it is discovered.
16. Existing employer or government health benefits
Some seniors have cover through a former employer, pension-related arrangement, government scheme or a spouse’s policy. Eligibility and benefits depend on the specific scheme and current rules. Confirm whether cover is active, which family members qualify, what hospitals participate, and whether the benefit has limits or renewal requirements. Do not cancel an existing policy until replacement cover is confirmed and continuity implications are understood. A personal policy may offer useful additional protection, but avoid assuming two policies will automatically pay every expense in full.
17. Claims: documents seniors and families should keep

Keep the policy schedule, health cards, insurer helpline, identity documents, prescriptions, investigation reports, admission notes, discharge summary, itemised hospital bills and payment receipts organised. Follow the insurer’s pre-authorisation or reimbursement instructions and timelines. For an emergency, do not delay necessary medical care while trying to complete paperwork; notify the insurer as soon as reasonably possible. Retain copies and reference numbers for submitted documents. If a claim is reduced or denied, request the reason in writing and compare it with the actual policy wording.
18. Common exclusions and non-payable expenses
Exclusions and non-payable items differ by policy. They may relate to particular treatments, services, circumstances, non-medical consumables or expenses that do not satisfy the coverage definition. A benefit mentioned in a brochure may have limits or conditions in the contract. Read the exclusions section, sub-limits, definitions and Customer Information Sheet. Ask the insurer to clarify any treatment or condition that is particularly relevant to the applicant. Keep the response in writing so the family can refer to it later.
19. How to compare two senior health plans

Compare plans using the same insured age, city, sum insured and benefit assumptions. Review premium, co-payment, deductible, room eligibility, pre-existing disease waiting period, disease-specific limits, restoration rules, network hospitals, renewal terms and claim process. Check whether the insurer can offer the plan to the applicant’s age and medical history. A plan with a lower price may leave more expenses with the policyholder; a higher price does not automatically mean broader cover. Base the decision on contract details and affordability.
20. Buying checklist before paying the premium

Before paying, verify the insurer and authorised intermediary, eligibility, sum insured, premium, payment schedule, policy period, waiting periods, exclusions, co-payment, deductible, room limits and renewal terms. Ensure every insured person’s name and date of birth are correct and all requested medical disclosures are complete. Read the proposal form and retain the submitted version. Save the payment receipt, policy wording, schedule and customer information document. If a salesperson makes a promise, ask for it to be confirmed in official policy documents or in writing by the insurer.
21. What if a claim is rejected or delayed?

First request the insurer’s written decision and the exact policy clause relied upon. Compare the stated reason with the medical records, submitted bills and policy wording. If information is missing, submit the requested documents and keep proof of submission. Use the insurer’s official grievance process if you believe the matter has not been handled correctly. Regulatory consumer resources and applicable grievance or ombudsman mechanisms may provide further routes, depending on the circumstances. Follow current official procedures and deadlines rather than relying on informal advice.
22. Tax treatment: verify current rules

Tax treatment of health-insurance premiums depends on the applicable law, eligibility and tax regime. Do not assume that every senior citizen or every premium qualifies for the same deduction. Keep receipts and review current guidance from the Income Tax Department, or ask a qualified tax professional about your circumstances. Choose a policy primarily for appropriate financial protection and sustainable affordability; a potential tax deduction should be a secondary consideration, not a reason to accept inadequate coverage.
23. Supporting an older parent through policy decisions

Involve the insured senior in decisions and explain key terms in plain language. Keep the insurer’s helpline, policy number and hospital preferences somewhere accessible to trusted family members, while protecting personal information. Review who is authorised to communicate with the insurer and what consent or documents may be required. Discuss how deductibles or co-payments would be paid if a claim occurs. Clear preparation can reduce confusion during stressful hospital admissions and help the family follow the correct process.
24. Frequently asked questions about senior citizen health insurance

**Can a senior with diabetes or hypertension get health insurance?** Some products may accept applicants with these conditions, subject to underwriting and terms; disclose them accurately and check waiting periods. **Does every policy cover pre-existing disease immediately?** No—coverage depends on the policy and applicable rules. **Is cashless treatment guaranteed?** No; it depends on network status, authorisation, eligible expenses and policy terms. **Should I choose the cheapest plan?** Compare exclusions and out-of-pocket costs as well as price. **Can premiums change?** They may change under permitted product and renewal rules; check official terms.
25. Where to verify official information

For current insurance regulation and consumer guidance, visit the Insurance Regulatory and Development Authority of India at irdai.gov.in. For specific benefits, limits and exclusions, consult the insurer’s issued policy wording and Customer Information Sheet. Use the insurer’s official contact channels to verify network hospitals and claim procedures. Avoid websites or agents promising guaranteed claim approval. General educational content cannot determine whether a specific treatment will be paid; the actual policy, facts of the claim and applicable rules govern the decision.
26. Final checklist: choose cover you can maintain
Choose a policy that balances meaningful hospital protection with realistic premiums and out-of-pocket costs. Check the waiting period for existing conditions, co-payment, room limits, nearby hospitals, renewal conditions and claim documentation. Complete disclosures honestly and store records securely. Reassess cover when health, income, residence or family circumstances change. Do not cancel existing insurance before understanding continuity and replacement terms. This article provides general information, not personalised insurance advice; confirm the latest product terms directly with the insurer before buying.
Related insurance guides

- Best Health Insurance for a Family in India
- Health Insurance Portability in India
- What to Do if a Health Insurance Claim Is Rejected or Delayed
- Benefits of Health, Car and Life Insurance
Disclaimer: This article is for general education only and does not endorse a specific insurer or product. Coverage and claim outcomes depend on the issued policy, disclosed facts and applicable rules. Verify current terms with the insurer and consult a qualified adviser if needed.
Benefits of Health Insurance, Car Insurance and Life Insurance in India
Insurance helps manage financial risk, but different policies protect against different events. This guide explains the benefits of health insurance, car insurance and life insurance in India, how the cover differs, and what to check before buying. Actual benefits depend on the policy wording, exclusions, limits and applicable law.
Introduction: Why insurance matters
Insurance is a financial risk-management tool. Instead of carrying the full cost of every covered event yourself, you pay a premium for a policy that may pay eligible benefits when specified events occur. The value is not that every claim is guaranteed; it is that suitable cover can make a serious, unexpected expense more manageable. In India, three important forms of protection are health insurance, motor insurance for a car, and life insurance. They address different risks and should not be treated as substitutes for one another.
1. Benefits of health insurance
Health insurance can help pay eligible hospitalisation and related medical expenses according to the policy terms. Its key benefit is reducing the chance that a major illness, surgery or accident forces a household to use all its savings or borrow at short notice. Depending on the plan, cover may include hospital room charges, surgery, medicines, diagnostic tests, pre- and post-hospitalisation expenses, day-care procedures and specified ambulance costs. Benefits, limits and waiting periods differ by product, so read the policy wording rather than assuming every medical bill is payable.
2. Helps protect savings during medical emergencies
A hospital admission can involve several costs at once: consultation, tests, medicines, procedures, room charges and time away from work. A suitable policy can pay eligible expenses directly through cashless treatment at a network hospital or reimburse eligible bills after submission, depending on the insurer’s process and approval. This can preserve savings for rent, education, loan repayments and day-to-day needs. However, deductibles, co-payments, room limits, exclusions and non-payable items can leave some expenses with the policyholder.
3. Supports family health planning
Individual health policies and family-floater plans serve different needs. A floater usually shares one sum insured among covered family members, which can be convenient but may be used substantially by one large claim. Compare the ages and health needs of everyone covered, the hospital network near home, waiting periods for pre-existing conditions, restoration benefits, maternity provisions if relevant, and renewal terms. Employer-provided cover may be useful, but personal cover can offer continuity when employment or benefits change.
4. Potential tax benefits of health insurance
Eligible health-insurance premiums may qualify for deductions under Section 80D of India’s Income-tax Act, subject to current law, eligibility conditions, age-related limits, payment rules and the tax regime chosen. Tax treatment can change, and deductions are not the main reason to buy inadequate or unsuitable cover. Check current Income Tax Department guidance or consult a qualified tax professional before relying on a deduction. Keep premium receipts and policy documents with your tax records.
5. Benefits of car insurance
Car insurance can protect against defined financial liabilities arising from vehicle use. In India, third-party motor insurance is legally required for vehicles used on public roads. It helps cover specified legal liability for injury, death or property damage to third parties, subject to applicable law and policy terms. A comprehensive package generally combines third-party liability with own-damage cover for insured damage to your vehicle, but the exact scope depends on the selected policy and add-ons.
6. Helps manage repair costs after covered damage
Accidents, fire, theft and certain natural events can result in expensive vehicle repairs or loss. If the event is covered, own-damage insurance may pay eligible repair or loss costs after applying deductibles, depreciation and other policy conditions. A cashless garage network can simplify settlement where available and approved. It is still important to notify the insurer promptly, document the incident, follow survey requirements and obtain approval before proceeding with repairs when the policy requires it.
7. Third-party versus comprehensive car insurance
Third-party-only cover addresses specified liabilities to others; it does not ordinarily pay for damage to your own car. Comprehensive cover adds own-damage protection for insured events, subject to exclusions and terms. Optional covers such as zero depreciation, engine protection, roadside assistance or return-to-invoice benefits may be available for eligible vehicles. These add-ons have conditions and extra costs. Compare insured declared value, deductibles, exclusions, claim service, repair network and premium—not price alone.
8. Benefits of life insurance

Life insurance is designed to provide a financial benefit when the insured person dies during the period or under the conditions specified in the policy. For a household that depends on one or more earners, this money can help surviving family members meet living costs, repay eligible debts, continue children’s education or adjust to a loss of income. The amount and timing of benefits depend on the policy type, sum assured, exclusions, disclosures and claim assessment. Keep nominee details and contact information current.
9. Term insurance and financial protection for dependants
Term life insurance offers life cover for a selected period and is often used to protect dependants at a comparatively straightforward cost. It generally pays the stated death benefit if a valid claim meets policy conditions during the term; a basic term plan usually has no maturity payout if the insured survives the term. Choose cover by assessing income replacement, outstanding loans, dependants, education goals, existing assets and the years until financial responsibilities are likely to reduce. Disclose medical history and lifestyle information accurately.
10. How life insurance differs from savings or investment products
Some life policies combine insurance with savings or investment features, while term insurance focuses on protection. Bundled products can have charges, surrender conditions, lock-in rules, returns that are not guaranteed, or benefits that depend on market performance. Compare the protection amount, premium duration, total premiums, guaranteed versus non-guaranteed benefits, surrender value and alternatives. Do not buy a product solely because it is described as an investment or offers a tax feature; understand the actual contract and whether it meets your goal.
11. How the three types of insurance work together
Each policy covers a different financial exposure. Health insurance is intended for eligible medical costs; car insurance covers specified motor liabilities and, when selected, own-vehicle damage; life insurance can provide a death benefit to nominated beneficiaries. A household may need all three, but the right amount and structure depend on health needs, vehicle use, income, dependants, existing employer benefits and budget. Review the policies together each year so that premiums remain affordable and cover reflects changes in family circumstances.
12. What to check before purchasing any policy
Read the policy wording, product brochure and Customer Information Sheet where provided. Confirm the insured person or vehicle, sum insured or assured, premium and payment schedule, waiting periods, deductibles, co-payments, exclusions, claim notification process, renewal conditions and cancellation or surrender rules. Check the insurer’s official website and verify that the intermediary is authorised. Ask for written answers to any unclear point and save the proposal form, policy schedule, receipts and communications.
13. Common insurance mistakes to avoid

Common mistakes include choosing only by the lowest premium, withholding health or lifestyle information, assuming every hospital or garage is cashless, overlooking waiting periods, buying insufficient life cover, and allowing a policy to lapse. Never assume an online summary overrides the actual policy wording. Keep reminders for renewals, update nominees and contact details, and inform family members where policy documents are stored. For claims, follow the insurer’s stated procedure and retain copies of all submissions.
14. Frequently asked questions
**Is health insurance necessary if I am young?** Medical costs can occur at any age; whether and how much cover to buy depends on your circumstances and budget. **Is third-party car insurance enough?** It meets the basic legal requirement, but it generally does not cover damage to your own vehicle. **Does term insurance pay if I survive the term?** A basic term plan generally does not, unless a specific return-of-premium feature applies. **Can a claim be rejected?** Claims may be declined or limited under policy terms, exclusions, material non-disclosure or other applicable grounds. Read the wording and ask the insurer about uncertainties.
15. Practical next steps
Start by listing the risks that would be hardest for your household to absorb: a major medical bill, a car accident liability or loss of an income earner. Compare policies from authorised insurers on the same assumptions, not just headline price. For health cover, inspect waiting periods and hospital access; for car cover, compare liability, own-damage terms and add-ons; for life cover, calculate the financial needs of dependants. Verify details directly with the insurer and seek regulated professional advice when needed. This article is general educational information, not personalised financial or insurance advice.
16. Health insurance: cashless treatment and reimbursement
Cashless treatment generally means the insurer or its administrator settles approved expenses with a network hospital, subject to authorisation and policy terms. It does not mean every service or amount is automatically free. The hospital may ask for a pre-authorisation request, and non-covered items or expenses above limits can remain payable by you. Reimbursement means you pay first and submit the required bills and records for assessment. Before admission, check the insurer’s current hospital network and process; in an emergency, prioritise appropriate medical care and notify the insurer as soon as reasonably possible under the policy instructions.
17. Car insurance: what can affect a claim
A claim outcome can depend on the type of cover, cause of loss, driver and vehicle details, policy validity, compliance with legal requirements and timely notification. Own-damage claims may involve a compulsory deductible, voluntary deductible, depreciation or exclusions. Third-party claims follow the applicable legal process. Do not admit liability or promise settlement on behalf of an insurer at the scene; ensure safety, contact the authorities where appropriate, record relevant details and follow the insurer’s instructions. Keep the policy number and emergency contact accessible.
18. Life insurance: nominations, disclosures and keeping records
A life policy is most useful to intended beneficiaries when its records are accurate and easy to locate. Complete proposal questions honestly, including medical history, tobacco use, occupation and other material facts requested. Review nominee details after marriage, a child’s birth, separation or another major family change, and understand how nominations operate under applicable law and policy terms. Tell a trusted family member where the policy schedule, premium receipts and insurer contact details are stored. Keep premiums current so the policy does not lapse unexpectedly.
19. How much cover is appropriate?
There is no single correct sum insured for every household. For health cover, consider local hospital costs, family size, age, existing conditions, employer benefits and whether a super top-up policy could fit your needs. For car insurance, consider the vehicle’s value, how much repair cost you could bear, legal liability and your usage pattern. For life insurance, estimate dependants’ living costs, outstanding loans, future education goals and income replacement, then account for assets and existing cover. Avoid selecting a figure solely because an advertisement suggests it.
20. Insurance review checklist for every year
Set aside time before each renewal to review whether the policy still fits. Check the insured names and details, sum insured or assured, premium due date, exclusions, waiting periods, deductibles and claim contact channels. For health insurance, review network hospitals and changes in family health needs. For car insurance, update vehicle details and compare own-damage cover and relevant add-ons. For life insurance, reassess dependants, debts and future responsibilities. Store digital copies securely and avoid sharing policy documents or identity details with unverified agents.
21. Where to verify insurance information in India

Use official sources when checking regulatory rules, consumer protections, insurer registration or tax provisions. The Insurance Regulatory and Development Authority of India (IRDAI) publishes regulatory and consumer information at irdai.gov.in. For tax questions, consult the Income Tax Department at incometax.gov.in. For specific benefits, exclusions and claim requirements, the issued policy wording and written clarification from the insurer are the primary documents to review. Be cautious of guaranteed-claim promises or pressure to purchase immediately.
22. Build a balanced protection plan around your budget
Insurance should protect against financial shocks without making monthly expenses unmanageable. List essential household costs, loan repayments, emergency savings and current policies before deciding what premium is affordable. Prioritise risks that could create a major financial setback, and avoid duplicating benefits without understanding how the policies coordinate. A low premium may come with a higher deductible, narrower coverage or important exclusions; a higher premium is not automatically better either. Compare the same cover features across insurers and check the insurer’s claim process, service channels and policy wording.
Keep emergency savings as well as insurance: a policy may not cover every expense, and claims can take time or require documents. Revisit the plan when you change jobs, buy a vehicle or home, take a loan, have a child, or become responsible for another family member. If you are uncertain about complex exclusions, tax treatment or suitable cover, request written clarification from the insurer or consult an appropriately qualified, authorised adviser. Never rely only on an agent’s verbal promise.
Helpful related guides

- Insurance in India: Types, Coverage and How to Choose
- Family Health Insurance in India
- Car Insurance Renewal: Comprehensive vs Third-Party
- How Much Term Life Insurance Cover Do You Need?
Disclaimer: This is general educational content, not a recommendation for a particular insurer or policy. Policy terms and tax laws can change. Confirm current details with the insurer, IRDAI resources and the Income Tax Department before making a decision.
Benefits of Walking Daily: Health Benefits, Beginner Plan and Safety Tips
Walking is one of the simplest ways to add regular movement to everyday life. It can support heart health, mood, mobility and general fitness without requiring a gym membership or specialised equipment. The right amount depends on your current activity, health, age and surroundings. This guide explains practical benefits, how to start safely and how to make walking a routine you can maintain.
What are the benefits of walking daily?

Walking is an accessible form of physical activity that can help improve cardiovascular fitness, support blood pressure and blood glucose management, strengthen muscles and bones, improve mood and make it easier to meet weekly activity goals. Benefits depend on frequency, pace, duration, starting fitness and health conditions. You do not need to begin with long walks or a specific step count. A comfortable, repeatable routine is a useful starting point, and short bouts can add up across the day.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
How walking supports heart health

Brisk walking raises the heart rate and can improve aerobic fitness over time. Regular physical activity is associated with better cardiovascular health and can complement management of blood pressure and cholesterol. Walking does not replace prescribed medication or clinical follow-up. If you have heart disease, significant breathlessness or other medical concerns, ask your clinician what intensity is appropriate. Start at a pace that lets you speak comfortably, then build duration gradually rather than suddenly pushing for speed.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking and blood glucose management

Muscles use glucose during activity, so walking can support blood glucose management as part of an overall care plan. The effect varies with meal timing, intensity, medication and individual health. People who use insulin or medicines that can cause low blood glucose should ask their care team how to exercise safely and whether they need to monitor glucose or carry a fast-acting carbohydrate. Do not change medication doses simply because you have started walking without professional guidance.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking and healthy weight management

Walking increases daily movement and energy use, but weight change depends on many factors, including food intake, sleep, medicines, health conditions and consistency. A walk can be valuable even if body weight does not change. Focus on building a sustainable routine, improving stamina and feeling better rather than expecting rapid weight loss. Avoid using exercise as punishment for eating. If weight management is a goal, combine movement with realistic eating habits and seek qualified advice when needed.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Benefits for mood, stress and mental wellbeing

A walk can provide a break from work, study or household demands and may help some people feel calmer or more alert. Walking outdoors can also offer daylight, contact with nature and social connection. These effects vary and walking is not a substitute for mental-health care when symptoms are persistent or severe. Choose a safe route and pace that feels restorative rather than adding pressure to reach a target. A short walk is still worthwhile when a longer session is not practical.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking, sleep and daily energy

Regular daytime activity may support sleep quality for some people and can help establish a predictable daily rhythm. Avoid forcing a strenuous late-night walk if it leaves you feeling wired or makes it harder to wind down. Sleep also depends on schedule, caffeine, stress, light exposure and medical factors. If insomnia, loud snoring or daytime sleepiness persists, seek appropriate assessment instead of relying on exercise alone.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Joint mobility, muscles and bones

Walking uses the muscles of the legs and trunk and places weight through the skeleton, which can be part of a bone-health routine. Comfortable walking can help maintain everyday mobility, but it may not be sufficient strength training for all muscle groups. If you have arthritis, a recent injury or pain, begin with a manageable distance and suitable surface. Increase gradually and seek advice if pain worsens, swelling develops or walking changes your gait.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
How many minutes should you walk?

Public-health guidance commonly recommends that adults aim for at least 150 minutes of moderate-intensity aerobic activity per week, alongside muscle-strengthening activity on two or more days when possible. This is a general target, not a requirement to meet immediately or a rule that suits every medical condition. Start from your current activity level and build toward a suitable goal. If you are inactive, even short sessions can be a meaningful first step.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
What is a moderate walking pace?

At a moderate pace, breathing is faster but you can usually talk in sentences; singing may feel difficult. The exact speed varies with age, fitness, terrain, temperature and health. A brisk pace for one person may be uncomfortable for another. Use perceived effort and symptoms rather than copying another person’s speed. If you cannot speak comfortably, feel faint or develop unusual breathlessness, slow down or stop and assess what is happening.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
A beginner plan for the first two weeks

Start with a duration that feels manageable, such as five to ten minutes on most days if that is appropriate for your health and current ability. Repeat the same comfortable routine for several sessions before adding a few minutes. Include easy warm-up and cool-down walking. If you experience persistent pain, unusual fatigue or symptoms that worry you, pause and seek advice. People who already walk regularly can begin at a higher level, but progression should still be gradual.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
A simple weekly walking schedule

Spread walks across the week according to your routine. For example, begin with a short walk on five days, add a slightly longer session when comfortable and keep one or more lighter days for recovery. This is an example, not a prescription. A few ten-minute walks can be easier to fit around work than one long session. Build the schedule around your life so it remains realistic during busy weeks, travel or bad weather.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking after meals: what to know

Some people find a gentle walk after a meal helps them build a routine and supports post-meal glucose management. Keep the pace comfortable, especially after a large meal, and consider any medical advice you have received. People taking glucose-lowering medication should discuss safe activity planning with their clinician if low blood glucose is a concern. Stop if you feel dizzy, weak, nauseated or otherwise unwell. Walking after meals is optional, not a requirement for everyone.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Choose safe footwear and comfortable clothing

Wear shoes that fit securely, feel comfortable and provide suitable grip for your route. New shoes should not cause blisters or pressure points. Choose breathable clothing appropriate to the weather and use reflective elements when walking in low light. If you have reduced foot sensation, foot ulcers or circulation problems, ask a clinician about appropriate footwear and foot checks before increasing walking. Replace footwear when it is worn out or no longer feels supportive.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Hydration, heat and weather precautions

In hot or humid weather, walk during cooler hours, choose shade and take breaks. Drink fluids according to thirst and your health needs; some people with heart or kidney conditions have specific fluid advice from their clinician. Do not ignore signs of heat illness such as marked weakness, dizziness, nausea or confusion. In poor air quality, extreme cold, storms or unsafe conditions, move the session indoors or postpone it. Adjust pace and duration to the environment.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking safely outdoors

Choose routes with safe crossings, adequate lighting and surfaces that suit your balance and mobility. Stay alert near traffic and avoid looking at your phone while crossing roads. In isolated areas, consider walking with another person, sharing your route or choosing a busier location. Use recognised paths and follow local rules. If walking at dawn or after dark, improve visibility and be aware of your surroundings rather than relying only on headphones or navigation apps.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Indoor walking and alternatives

A corridor, shopping centre where permitted, treadmill or indoor track can help maintain a routine when weather or safety makes outdoor walking difficult. If space is limited, walk around a room and add gentle marching or movement breaks. Use stable support if balance is uncertain and avoid cluttered areas. Indoor sessions count as activity when they raise movement to a suitable level. Consistency matters more than the scenery or having specialised equipment.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking for older adults and balance concerns

Older adults may benefit from walking, but falls risk, vision, medications, balance and joint conditions can affect what is safe. Start on a familiar, even route and use prescribed walking aids correctly. If you have fallen recently, feel unsteady or avoid activity because of fear of falling, ask a clinician or physiotherapist about an individual plan. Balance and strength exercises may be useful additions. Do not walk alone in conditions that make you feel unsafe.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking with diabetes or other chronic conditions

People with diabetes, heart or lung conditions, kidney disease or other chronic illnesses can often be physically active, but the plan may need adjustment. Ask about intensity, foot care, medication timing, hydration and warning symptoms that apply to you. Wear appropriate footwear and check your feet if you have reduced sensation. Do not exercise through chest pain, faintness or severe breathlessness. The right plan depends on your medical history, current treatment and baseline fitness.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
How to stay motivated without chasing step counts

Link walking to an existing habit, such as a lunch break or evening routine. Choose a route you enjoy, listen to music only when it is safe and invite a friend if social support helps. Track minutes or how you feel rather than treating a step count as a measure of personal worth. Missed days are normal; restart with a manageable session. If tracking makes you anxious or compulsive, stop tracking and focus on comfort and consistency.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Common walking mistakes to avoid

Common mistakes include increasing distance too quickly, ignoring persistent pain, wearing unsuitable shoes, walking through extreme heat and assuming faster is always better. Another mistake is starting with a target that does not fit your current ability and then abandoning the routine. Build gradually, rest when ill and adjust to weather and symptoms. Do not use a phone while crossing roads, and avoid pushing through chest pain, faintness or severe breathlessness.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
When to stop and seek medical advice

Stop exercising and seek urgent medical care for chest pain or pressure, fainting, severe or unusual breathlessness, sudden weakness or other serious symptoms. New leg swelling, persistent joint pain, repeated dizziness or a major change in exercise tolerance should be discussed with a clinician. People with known medical conditions should follow their individual advice. Do not interpret alarming symptoms as a normal sign that the workout is effective.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Walking is useful, but variety matters

Walking is an excellent way to build aerobic activity, but a well-rounded routine may also include muscle strengthening, balance work and mobility according to ability. It does not train every muscle equally and may not provide the right stimulus for every fitness goal. Add suitable strength exercises on separate days or as advised. Rest and recovery are important too. A sustainable routine should support daily life, not leave you continually exhausted or in pain.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Frequently asked questions about daily walking

Is 10,000 steps compulsory? No; it is not a universal medical requirement. Can short walks count? Yes, activity can be accumulated in manageable bouts. Is walking enough for everyone? It is a useful foundation, but some people need additional strength, balance or tailored activity. Should you walk when sick? Rest or seek medical advice when symptoms warrant it. The best routine is safe, appropriate to your health and repeatable over time.
Choose a pace and route that fit your circumstances, and follow individual medical advice when a health condition affects exercise safety.
Related reading: building a sustainable exercise routine, healthy habits for busy families and benefits of yoga.
For general physical activity guidance, see the World Health Organization’s physical activity guidance. Contact The Infinity Company on WhatsApp: +91-7290007100
Benefits of Superfoods: Nutrient-Rich Foods, Indian Examples and Smart Eating Tips
“Superfood” is a popular marketing term, not a formal medical category. It usually describes foods that provide useful nutrients such as fibre, protein, vitamins, minerals or unsaturated fats. No single food prevents every disease or replaces an overall balanced diet. This guide explains the practical benefits of nutrient-rich foods, Indian examples, affordable ways to include them and why supplements or expensive powders are not always necessary.
What does superfood actually mean?

The term usually refers to foods with a high concentration of one or more useful nutrients, but there is no official list that makes a food universally superior. A food’s value depends on the rest of the diet, portion size, preparation, affordability and personal health needs. Lentils, seasonal vegetables, fruit, nuts and whole grains can be nutritious without premium branding. Think of “superfood” as a reminder to choose variety, not a promise of a special medical effect.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Benefits come from the overall dietary pattern

A balanced pattern that includes vegetables, fruit, pulses, whole grains, nuts or seeds and suitable protein sources can help meet nutrient needs. Fibre supports bowel regularity and can help with fullness; protein supports tissue maintenance; and unsaturated fats contribute energy and help the body absorb certain vitamins. The benefit comes from regular, varied eating over time, not from adding one trendy ingredient to an otherwise unbalanced diet.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Leafy green vegetables

Spinach, mustard greens, fenugreek leaves and other local greens provide fibre and several vitamins and minerals. Different greens have different nutrient profiles, so variety is more useful than relying on a single type. Wash produce carefully and cook it appropriately. People with specific medical conditions or dietary restrictions may need individual advice about certain foods, but most people can build greens into meals through dals, sabzi, soups or mixed dishes.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Seasonal fruit and berries

Guava, oranges, papaya, bananas, apples and other seasonal fruits contribute fibre, water and micronutrients. The best choice is often the fruit that is fresh, affordable and eaten regularly. Whole fruit generally provides more fibre and tends to be more filling than juice. Frozen fruit can also be useful where available. No single fruit is required for good health, and people managing blood glucose can discuss portions and meal planning with their clinician or dietitian.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Pulses, beans and lentils

Dal, rajma, chana, lobia and other pulses offer plant protein, fibre and minerals. They can be economical staples and help make meals more satisfying. Soaking and cooking them properly improves texture and digestibility for many people. Combine pulses with grains and a variety of vegetables across the day to broaden nutrient intake. Canned options can be convenient; compare sodium content and rinse when appropriate.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Nuts and seeds

Peanuts, almonds, walnuts, sesame, flaxseed, chia and pumpkin seeds provide varying amounts of unsaturated fats, protein, fibre and micronutrients. A small portion can add flavour and nutrient density to meals, but nuts and seeds are energy-dense, so large amounts can add substantial calories. Choose unsalted options where possible and consider allergies. Ground seeds may be easier to incorporate into foods, but they are not a substitute for varied meals.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Whole grains and millets

Oats, whole-wheat atta, brown rice and millets such as ragi, jowar and bajra can contribute fibre and other nutrients. Whole grains may support fullness and a healthier overall dietary pattern when they replace some refined grains. The best grain depends on availability, preference, cooking traditions and individual needs. No grain is automatically ideal for everyone; variety and portion balance matter more than a fashionable label.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Fermented foods and gut health

Curd and other fermented foods can fit into a balanced diet and may provide beneficial microbes depending on the product and preparation. Their effects vary by food and person, and not every fermented product is a proven probiotic treatment. Choose safe preparation and storage, and check added sugar and salt in packaged foods. If you have a medical condition affecting immunity or digestion, ask a healthcare professional about specialised products or supplements.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Protein-rich foods for everyday meals

Eggs, dairy, fish, poultry, tofu, soy foods and pulses can help meet protein needs, depending on dietary preferences. Protein is important for maintaining tissues and supporting normal body functions, but individual requirements vary with age, activity, pregnancy and health conditions. Spread suitable sources across meals rather than depending on a single shake or powder. People with kidney disease or other conditions may need personalised protein advice from their clinician.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Healthy fats and food quality

Nuts, seeds and some plant oils provide unsaturated fats, which can replace some saturated fats in a balanced eating pattern. Portion size still matters because oils and nuts are energy-dense. Whole foods often provide several nutrients together, while a refined oil or isolated nutrient does not offer the same combination. Choose cooking methods and amounts that fit your overall diet, budget and medical guidance.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
How fibre supports digestion and fullness

Fibre from vegetables, fruit, pulses, nuts and whole grains helps support bowel regularity and may improve fullness. Increase fibre gradually and drink fluids appropriate to your health needs, because a sudden large increase can cause gas or discomfort. Some digestive conditions require tailored advice about fibre type or quantity. Whole foods offer a mixture of fibres and other nutrients, so variety is generally more practical than relying on a single fibre powder.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Antioxidants: useful, but not magic

Many plant foods contain compounds with antioxidant activity, alongside vitamins and minerals. Laboratory findings do not automatically mean that a concentrated supplement prevents disease in people. Eating a range of colourful vegetables and fruits is a sensible way to obtain diverse nutrients. Avoid claims that a food “detoxes” the body or guarantees protection from illness; the body already has systems for processing and eliminating waste, and medical claims require strong evidence.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Affordable Indian superfood choices

Everyday options such as seasonal vegetables, guava, amla, pulses, peanuts, curd, eggs where eaten, and locally available whole grains can be nutrient-rich without being expensive. Frozen produce or plain packaged pulses may also be useful when fresh choices are limited. Compare cost per serving, storage life and preparation time rather than buying based on a premium label. A practical food that your household enjoys and can afford consistently is more useful than an expensive product left unused.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Build a balanced Indian plate

A practical meal can include vegetables, a suitable protein source, whole grains or another staple, and fruit or curd where appropriate. The proportions depend on appetite, activity, cultural preferences and health needs. Dal with roti and sabzi, rice with rajma and vegetables, or eggs with whole-grain toast and fruit are examples rather than strict prescriptions. Use the plate as a flexible guide, not a rigid rule for every person or medical condition.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Breakfast ideas using nutrient-rich foods

Try oats with nuts and fruit, vegetable poha with peanuts, eggs with whole-grain roti, or curd with fruit and seeds, depending on your preferences. A breakfast does not need a special powder or imported ingredient to be nourishing. Consider protein, fibre, portion size and convenience. If you are not hungry early in the day or have a condition requiring a specific meal schedule, adapt the plan with appropriate professional advice.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Lunch and dinner ideas

Include a pulse, egg, dairy, tofu, fish, poultry or another suitable protein source with vegetables and a staple. Examples include dal, seasonal sabzi and roti; rajma with rice and salad; or a vegetable-and-tofu bowl with whole grains. Variety across the week helps broaden nutrient intake. Adjust salt, oil and portion sizes to personal needs, and follow clinician guidance for conditions such as kidney disease or diabetes.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Smoothies, juices and powders

Blended drinks can be convenient, but large smoothies may contain more energy than expected and juices usually provide less fibre than whole fruit. Commercial powders vary widely in ingredients, quality and added sugar. Check labels, serving size and independent quality information where available. Supplements can interact with medicines or be unsuitable for some conditions. Do not use a powder as a replacement for a balanced diet unless a qualified professional recommends a specific product for a clear reason.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Do superfoods help with weight management?

Foods with fibre and protein can contribute to fullness, but weight change depends on the overall balance of food intake, activity, sleep, medicines and health factors. Nuts and seeds are nutritious but calorie-dense; juices and sweetened smoothies can add energy quickly. No food burns fat on its own. Aim for a sustainable pattern that fits your preferences rather than a restrictive “superfood diet” that is difficult to maintain.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Superfoods and blood glucose

Whole grains, pulses, vegetables and whole fruit can fit into many eating patterns for blood glucose management, but portions and total meal composition matter. Fruit juice, sweetened drinks and products marketed as healthy can still deliver substantial sugar. Individual responses vary. If you have diabetes or take glucose-lowering medicines, work with your clinician or dietitian on meal timing, portions and medication safety instead of relying on a food trend.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Superfoods and heart health

A diet pattern rich in vegetables, fruit, pulses, whole grains, nuts and unsaturated fats can support cardiovascular health as part of broader habits. It does not replace prescribed medication, smoking cessation support, physical activity or blood pressure and cholesterol management. Avoid claims that one seed or fruit clears arteries or rapidly lowers cholesterol. People with diagnosed heart disease should follow their care plan and ask before using concentrated supplements.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Food safety, allergies and storage

Wash produce under safe running water, store perishable foods at suitable temperatures and cook high-risk foods thoroughly. Check labels for allergens and cross-contact warnings when needed. Nuts, seeds, dairy, eggs and other foods can cause allergic reactions in susceptible people. Store oils, nuts and seeds away from excessive heat and light to preserve quality. Discard foods that appear spoiled and follow local food-safety advice for preparation and storage.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
When a supplement may be appropriate

A supplement may be useful when a deficiency, increased requirement or specific clinical indication has been identified. The choice and dose depend on the person and the nutrient; more is not always better. High doses of some vitamins and minerals can cause harm or interact with medicines. Discuss symptoms, diet and existing supplements with a healthcare professional, and avoid replacing necessary treatment with an unverified product.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
How to spot exaggerated nutrition claims

Be cautious when a product promises rapid weight loss, guaranteed disease prevention, “detoxification” or a cure for multiple unrelated conditions. Testimonials and influencer promotions do not establish effectiveness. Look for clear ingredients, realistic claims, transparent serving sizes and credible evidence relevant to people, not only laboratory studies. If a claim urges you to stop prescribed treatment or buy immediately, treat it as a warning sign and seek independent advice.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Create a simple weekly food plan

Choose a few vegetables, fruits, pulses and protein sources for the week, then plan meals around foods your household already likes. Reuse ingredients across dishes to reduce waste and cost. Keep easy options available, such as roasted chana, fruit or plain curd if suitable. A flexible plan works better than buying a long list of products for a short-lived challenge. Review the plan based on hunger, schedule, budget and what you actually eat.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Frequently asked questions about superfoods

Are superfoods essential? No; a varied, balanced diet matters more than a particular branded food. Are expensive powders better? Not necessarily; compare ingredients and evidence. Can one food prevent disease? No single food offers that guarantee. What should you start with? Add affordable vegetables, fruit, pulses, whole grains and suitable protein sources that you enjoy. For a medical condition or restricted diet, ask a qualified professional for tailored advice.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
For more practical guides, explore healthy eating on a budget, healthy habits for busy families and benefits of yoga.
Reasons for Hair Fall: Common Causes, Warning Signs and What to Do
Hair shedding is normal, but a noticeable increase, widening part, receding hairline or bald patch can have many possible causes. Identifying the pattern and timeline is more useful than buying a product based on an advertisement. This guide explains common reasons for hair fall, sensible hair-care steps and when professional assessment can help. It is general information, not a diagnosis; treatment depends on the cause.
How much hair shedding is normal?

Hair naturally moves through growth, transition and resting phases, so some strands come out during washing, brushing and daily activities. The amount varies with hair length, washing frequency, styling and individual hair cycles. A sudden change from your usual pattern, visible thinning or persistent shedding deserves attention. Counting every strand can become stressful and is not a reliable diagnosis. Instead, note when the change began, whether it is diffuse or patchy, and whether other symptoms are present.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Genetics and pattern hair loss

Hereditary pattern hair loss is a common cause of gradual thinning. It may appear as a receding hairline or thinning around the crown, or as widening of the part and reduced density. It usually develops over time rather than overnight. Family history can be a clue, but it does not prove the cause. A dermatologist can assess the pattern and discuss evidence-based options, expected benefits, limitations and possible side effects before treatment begins.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Stress, illness and major life events

Physical or emotional stress can sometimes trigger increased shedding after a delay. High fever, surgery, severe illness, major weight loss or a demanding life event may shift more hairs into a resting phase. Shedding may become noticeable weeks or months later and can improve as the trigger resolves, although recovery takes time. If shedding is heavy, persistent or accompanied by other symptoms, seek medical advice rather than assuming stress is the only explanation.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Nutrition and inadequate calorie intake

Hair growth depends on adequate overall nutrition. Restrictive diets, rapid weight loss or inadequate intake of protein and key nutrients may contribute to shedding in some people. A balanced diet with sufficient energy and varied protein sources is a sensible foundation. Supplements are not automatically helpful, and excess intake of some nutrients can be harmful. If diet has changed substantially or deficiency is suspected, a clinician can decide whether testing or a dietitian referral is appropriate.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Iron deficiency and other medical causes

Low iron stores and certain medical conditions can be associated with hair loss. The likelihood depends on the person’s history, symptoms and risk factors; not everyone needs the same laboratory tests. Do not start iron or other high-dose supplements without advice, because unnecessary supplementation can cause harm. A clinician may review diet, bleeding history, medicines and other symptoms before deciding whether tests are indicated.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Thyroid and hormonal changes

Thyroid disorders and some hormonal changes may affect hair growth. Changes after pregnancy, during menopause or alongside symptoms such as fatigue, temperature intolerance, menstrual changes or unexplained weight changes may be relevant. These symptoms have many possible explanations, so they should not be used to self-diagnose. Discuss the timeline and associated symptoms with a healthcare professional who can determine whether evaluation is appropriate.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Scalp conditions, inflammation and infection

Itching, scaling, redness, pain, broken hairs or areas of reduced density can point toward a scalp condition rather than routine shedding. Fungal infection, inflammatory skin disorders and other conditions may require specific treatment. Avoid applying harsh home remedies or sharing combs and personal grooming tools when infection is possible. Seek assessment promptly if the scalp is painful, inflamed, crusted or showing spreading bald patches.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Hair breakage is not the same as shedding

Short broken strands, split ends and uneven lengths may indicate damage to the hair shaft rather than hair falling from the root. Heat, chemical processing, tight hairstyles and rough detangling can weaken hair. Examine the overall pattern and styling history, but avoid pulling hairs to test them. Gentle handling, less heat and avoiding repeated chemical treatments may reduce breakage while a professional evaluates persistent thinning.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Tight hairstyles and traction

Repeated tension from tight ponytails, braids, extensions or other styles can stress hair follicles, especially around the hairline. Early traction-related hair loss may improve when the tension stops, but long-standing damage can become permanent. Choose comfortable styles, vary how hair is tied and avoid pain or persistent pulling. If the hairline is receding or the scalp feels sore, loosen the style and seek advice rather than continuing the same practice.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Heat styling and chemical treatments

Frequent high heat, bleaching, straightening and overlapping chemical treatments can cause dryness and breakage. Use the lowest effective heat, allow hair to dry where practical, and follow product instructions carefully. Do not combine strong treatments without understanding their compatibility. A conditioner may improve manageability but cannot repair every form of structural damage. If hair breaks suddenly after a chemical service or the scalp burns, stop the product and seek professional advice.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Medicines and medical treatment

Some medicines and medical treatments can affect hair growth, but never stop a prescribed medicine on your own because of hair shedding. Record when a medicine was started or changed and when the shedding began. A prescribing clinician can review the timing, alternatives and the risks of changing treatment. Hair changes may also reflect the underlying condition, so attributing them to one medicine without assessment can be misleading.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Postpartum hair shedding

Some people notice increased shedding after childbirth as hormonal patterns change. This can be distressing, especially when hair appears to come out during washing or brushing. It often improves over time, but persistent, severe or patchy loss should not automatically be attributed to postpartum changes. Adequate nutrition, gentle styling and support with recovery are sensible steps; a clinician can assess other possible causes when symptoms or the timeline are atypical.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Rapid weight loss and crash diets

Very restrictive eating and rapid weight changes can disrupt the body’s normal hair cycle. A diet that removes entire food groups without a plan may also make it harder to meet nutrient needs. Aim for sustainable changes, regular meals and sufficient protein and energy rather than crash dieting. If hair loss begins after major weight change, tell your clinician when the diet started and whether you have fatigue, dizziness or other symptoms.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Sleep, stress and everyday habits

Sleep and stress do not explain every case of hair loss, but poor recovery and difficult life circumstances can affect general wellbeing and may coincide with shedding. Set realistic sleep routines, build manageable movement into the day and use stress-support strategies that suit you. These steps complement, rather than replace, medical assessment when hair loss is pronounced or persistent. Avoid blaming yourself: hair loss often has multiple interacting factors.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
When to consult a dermatologist

Arrange an assessment if loss is sudden, persistent, patchy, associated with scalp symptoms or causing visible changes. Seek prompt care for painful inflammation, spreading lesions or signs of infection. Bring a list of medicines and supplements, relevant medical history, diet changes and photographs showing the progression over time. A clinician may examine the scalp and decide whether blood tests or further evaluation are warranted.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
What a hair-loss assessment may involve

A clinician usually asks about the onset, pattern, family history, recent illness, stress, nutrition, medicines and hair-care practices. They may examine the scalp and hair shafts and, when indicated, recommend targeted tests. There is no single universal panel suitable for every person. Ask what each test is intended to investigate and how the result would change the plan. This helps avoid unnecessary testing and random supplement use.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Treatment depends on the cause

Different causes need different approaches: a scalp infection, nutritional deficiency, hereditary pattern loss and traction-related damage are not treated in the same way. Some treatments require ongoing use and may have side effects or be unsuitable during pregnancy or for certain medical conditions. Ask about expected timelines, realistic outcomes, monitoring and alternatives. Be wary of claims promising guaranteed regrowth or results in a few days.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Be careful with oils, shampoos and supplements

Hair oils may help reduce dryness or improve manageability for some hair types, but they do not treat every cause of hair loss. Anti-dandruff products may help certain scalp symptoms, while ordinary shampoos cannot reverse hereditary thinning. Supplements are most useful when a deficiency or specific need is established. Avoid products that promise a cure, conceal ingredients or pressure you into expensive recurring purchases.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Build a gentle hair-care routine

Use a shampoo suited to your scalp, condition lengths as needed and detangle gently from the ends upward. Avoid aggressive brushing, excessive heat and styles that pull. Protect hair from repeated chemical damage and follow the instructions for any treatment. Routine changes may reduce breakage, but persistent shedding still needs assessment. Choose a manageable routine rather than purchasing many products at once.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Track changes without becoming preoccupied

Take occasional photographs under similar lighting and angles if you want to monitor density. Record the approximate start date, major health events and any new products or medicines. Avoid daily comparisons because normal variation in lighting, washing and styling can be misleading. If monitoring increases anxiety, let a clinician guide follow-up instead. The aim is to identify a meaningful pattern, not to measure every strand.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Questions to ask before starting treatment

Ask what diagnosis is most likely, what evidence supports the recommended treatment, how long results may take and what side effects to watch for. Clarify whether the plan requires ongoing use, follow-up visits or laboratory monitoring. Discuss pregnancy plans, existing conditions and all medicines or supplements. Ask how progress will be judged and when the plan should be reviewed if there is no improvement.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Myths and misleading hair-loss claims

Hair fall is not always caused by washing too often, and shampooing does not necessarily create the underlying problem. There is no one oil, food or supplement that cures every form of hair loss. Cutting hair may change how thick the ends look but does not alter follicle growth. Be cautious of dramatic before-and-after images and testimonials without credible evidence.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
A practical first-step checklist

Note the pattern and timeline, review recent illness and diet changes, loosen tight hairstyles, reduce damaging heat and chemical practices, and avoid self-prescribing high-dose supplements. Seek a dermatologist or clinician when loss is sudden, persistent, patchy or accompanied by scalp symptoms. Bring your questions and a list of medicines. A structured assessment is usually more useful than trying multiple products at once.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
Frequently asked questions about hair fall

Can stress cause shedding? It can contribute in some circumstances, but other causes may coexist. Does oil stop hair fall? Oil may help hair feel less dry but is not a universal treatment. Should everyone take biotin or iron? No; supplements should be based on need and professional advice. When should you seek help? Sudden, persistent, patchy or symptomatic hair loss merits assessment. Treatment and recovery timelines vary with the underlying cause.
Choose practical steps that fit your circumstances, and seek qualified professional guidance when symptoms, medical conditions or individual needs make general advice insufficient.
For more practical guides, explore healthy eating on a budget, healthy habits for busy families and benefits of yoga.
Travel Planning Checklist for India: Budget, Bookings, Documents and Safety
A successful trip starts well before departure. The best plans balance cost, comfort, safety and flexibility while leaving room for unexpected changes. This travel planning checklist is designed for domestic and international journeys from India, whether you are travelling alone, with family or in a group. Use the sections that match your itinerary, and verify current entry, transport and health requirements through official sources before you travel.
Start with your travel style and trip purpose

Decide whether the trip is for relaxation, adventure, culture, food, nature, shopping, work or visiting family. The purpose determines the destination, pace, transport and amount of planning required. Write down two or three priorities rather than trying to do everything. A beach break may need fewer transfers than a multi-city cultural trip, while a trek requires suitable fitness, equipment and weather planning. Share expectations with everyone travelling so the itinerary suits the group, not just the person who books it.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Choose the right season, not just the cheapest dates

Check typical temperatures, rainfall, humidity, daylight and seasonal closures for your destination. Peak season can bring higher prices and crowds; off-season travel can be cheaper but may involve weather disruption or limited services. For mountain, coastal and outdoor trips, look for official weather alerts and local advisories close to departure. Climate averages are useful for planning but cannot predict exact conditions. Keep an alternative indoor activity or flexible day in the itinerary when weather is likely to affect travel.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Set a realistic total budget

Estimate the full cost rather than comparing only flight or hotel prices. Include transport to the departure point, local travel, accommodation, meals, activities, entry fees, visas, insurance, connectivity, baggage and tips where customary. Add a contingency for unexpected costs, particularly on multi-stop or international trips. Decide which experiences matter most and where you can economise without compromising safety. A written budget with daily limits helps prevent a cheap booking from turning into an expensive holiday.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Compare transport options door to door

Compare total travel time, transfers, baggage rules, reliability and the cost of reaching stations or airports. A lower fare may require an overnight connection, separate tickets or a long transfer. For trains and buses, check departure and arrival stations carefully. For flights, review layover length and whether checked baggage is transferred through. If booking separate tickets, leave a generous buffer because a delay on the first leg may not protect you on the next.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Build a flexible itinerary

Group activities by neighbourhood or geographic area to reduce backtracking. Avoid scheduling every hour: travel between attractions, meals, queues and rest all take time. Identify the one or two experiences that matter most each day and leave optional stops for spare time. For longer trips, a lighter day after arrival or a demanding excursion helps reduce fatigue. Keep booking references and opening times accessible offline in case mobile data is unavailable.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Choose accommodation by location and total value

Check how far the property is from the places you plan to visit, the nearest transport, and the route you will use after dark. Compare the final price including taxes, cleaning fees, resort fees or other mandatory charges. Read recent reviews for cleanliness, noise, accessibility and cancellation handling. Confirm check-in hours, luggage storage, extra-bed rules and whether the room type matches your needs. A slightly higher nightly price can be worthwhile if it saves repeated taxi fares.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Read cancellation and change conditions before paying

Check whether the fare or room can be cancelled, changed or refunded, and note the relevant deadline and fees. “Free cancellation” may apply only until a specified local time or to selected components of a booking. Review separate rules for flights, accommodation, activities and transfers. Save the terms as well as the confirmation. If travel dates are uncertain, compare the cost of a flexible booking with the potential loss from a non-refundable one.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Verify passports, visas and entry rules

For international travel, check passport validity, visa or electronic authorisation requirements, permitted stay, transit rules and any additional documents. Use official government or embassy sources for the destination and transit countries. Rules depend on nationality, passport type, purpose and itinerary, so do not assume another traveller’s experience applies to you. Apply early enough to account for processing time, and avoid non-refundable arrangements until you understand the relevant entry requirements.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Check health, medication and accessibility needs

Consider whether the destination requires health precautions, vaccinations or medical documentation and consult an appropriate healthcare professional when necessary. Carry essential medication in original packaging where practical, with prescriptions or supporting documents for controlled or restricted medicines. Check airline and destination rules before travelling with medical equipment. Plan for mobility needs, dietary requirements, rest breaks and access to healthcare. If travelling with children or older relatives, tailor the schedule and accommodation to their needs.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Buy travel insurance that fits the trip

Read policy wording rather than relying on a headline benefit. Compare medical cover, emergency assistance, trip cancellation, interruption, baggage, delays, exclusions, excesses and claim deadlines. Activities such as trekking, skiing or motorcycling may require specific cover. Pre-existing conditions and high-value equipment may have special rules. Keep the policy number and emergency contact accessible offline. Insurance does not replace safe planning, and reimbursement may depend on evidence and timely notification.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Prepare a practical packing list

Start with destination climate, trip length, planned activities, laundry access and baggage limits. Pack versatile clothing, comfortable footwear, toiletries, chargers, adapters where needed and any activity-specific equipment. Keep essential medication, a change of clothes and critical documents in carry-on baggage when appropriate. Review restricted and prohibited items for the airline and destination. Avoid packing “just in case” items that add weight but are unlikely to be used; leave space for items acquired during the trip.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Protect documents and digital access

Store booking confirmations, insurance details, emergency contacts and copies of key documents securely. Keep access to originals in line with the destination’s requirements; a digital copy is useful but may not replace an original document. Enable device security and multi-factor authentication before departure. Save important information offline and ensure you can access email or booking accounts if your primary phone is lost. Avoid storing passwords or sensitive information in an unprotected note.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Plan money, cards and emergency funds

Check foreign transaction charges, ATM fees, card acceptance and cash needs. Notify your bank if it recommends travel notifications, and know how to freeze a lost card. Carry more than one payment option separately rather than keeping every card and all cash in one wallet. Use reputable exchange services and review the rate and fees before confirming. Keep a modest emergency reserve for transport, accommodation or essential purchases if a card or phone stops working.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Arrange mobile connectivity before departure

Compare roaming, local SIM and eSIM options based on your phone compatibility, destination coverage and data needs. Check activation steps, validity and whether calls or SMS are included. Keep access to booking confirmations and maps offline in case the connection fails. Use trusted networks for sensitive transactions and avoid unknown public charging ports. If using public Wi-Fi, verify the network name and use the security tools recommended for your devices.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Use local transport safely and efficiently

Research official transit passes, airport transfers, ticket validation rules and the last service of the day. For taxis or ride-hailing, use recognised booking channels where available and confirm vehicle and driver details before entering. Agree on the fare or meter arrangements when relevant. Check walking routes, weather and luggage burden before choosing to walk. For remote locations, arrange return transport in advance rather than assuming a ride will be available after an activity ends.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Book popular activities with care

Check whether an attraction needs timed entry, advance reservations, a guide or special equipment. Read what is included, the meeting point, minimum age, fitness requirements and cancellation terms. Verify the operator’s safety procedures for activities involving water, heights, wildlife or vehicles. Avoid pressure to pay immediately through an unfamiliar link. Keep booking receipts and the operator’s contact details, and arrive with enough time to find the correct meeting location.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Respect local customs and the environment

Research local dress expectations, photography restrictions, tipping customs, religious-site etiquette and rules around alcohol or public behaviour. Ask permission before photographing people, and follow signs at cultural or sacred locations. Choose responsible wildlife experiences that do not encourage harassment or unsafe contact with animals. Reduce waste, refill water where safe and permitted, and respect protected areas. Travelling considerately helps protect local communities and makes interactions more positive.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Plan for children, older travellers and groups

Agree on the pace, budget and must-do activities before booking. Keep essential contact information available, establish a meeting point in busy places and account for rest, meals and accessible facilities. For children, verify seat, identification and consent-document requirements for the route. For older travellers or people with mobility needs, confirm lifts, step-free access, transfer distances and medical support rather than relying on a general “accessible” label. Build flexibility into the plan when group needs differ.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Prepare for delays and disruptions

Keep essential items and a small amount of food or water accessible when appropriate. Save airline, railway, accommodation and insurance contacts. If a delay occurs, confirm the official status and options before paying for a replacement. Keep receipts for reasonable extra expenses and ask the provider what documentation is required. Separate bookings can mean separate responsibilities, so understand who is responsible for rebooking. Do not rely solely on screenshots of a schedule that may change.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Keep an emergency contact and check-in plan

Share the itinerary with a trusted contact, including accommodation details and expected arrival times where appropriate. Agree how you will check in and what they should do if they cannot reach you after a reasonable interval. Know the local emergency number and the location of relevant consular assistance when abroad. In a genuine emergency, contact local emergency services first. Do not publicly post live location or room details if doing so could compromise your privacy or safety.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Avoid common travel-planning mistakes

Frequent mistakes include underestimating transfer time, ignoring baggage limits, relying on one payment card, booking non-refundable services before checking entry rules and overfilling each day. Another risk is using unofficial sites that imitate airlines, hotels or government services. Verify the domain and booking details, and be cautious of pressure tactics or unusually low prices. A short pre-departure review of documents, transport, money, health needs and cancellations can prevent many avoidable problems.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Use a 7-day pre-departure checklist

One week before departure, reconfirm major bookings, check entry requirements and review the weather forecast. Confirm transport to the airport or station, accommodation check-in and any activity meeting points. Review insurance and medication needs, download maps and documents, and check baggage dimensions. Tell your bank or mobile provider anything needed for travel. Make copies of essential contact information and resolve any mismatch in passenger names or booking details early.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Use a final-day checklist

Check in where available, review the latest departure information and keep identification and required travel documents accessible. Charge devices and power banks in accordance with carrier rules, weigh baggage and confirm transport timing. Secure your home as appropriate and arrange care for pets or plants. Leave enough time for queues and unexpected road or transit delays. Before leaving, check that you have keys, medication, glasses, chargers and the payment methods you intend to use.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
After returning, close out bookings and expenses

Save receipts needed for reimbursement, expense reporting or insurance claims. Check card statements for unfamiliar transactions and report concerns through official channels. If baggage was lost or property damaged, follow the carrier’s reporting procedure and deadlines. Keep useful notes about transport, accommodation and activities while the experience is fresh; they can help with future planning. Secure travel documents and remove unnecessary copies of sensitive information from shared devices.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Related travel guides and final takeaway

For more planning help, read the first international trip checklist, the travel safety checklist and the travel packing checklist. The strongest travel plan combines realistic budgeting, verified documents, flexible timing, suitable insurance and sensible safety precautions. Confirm changing requirements through official sources shortly before departure, because policies and conditions can change.
Keep the relevant booking details and emergency information accessible, and reassess the plan if official advice, weather or transport conditions change.
Explore more from The Infinity Company: international trip checklist, travel safety guide, and packing checklist.
THE INFINITY COMPANY
Need Help Planning Your Trip?
Contact The Infinity Company for travel enquiries and assistance with your travel plans.
CHAT ON WHATSAPPCALL: +91-7290007100
WhatsApp: +91-7290007100 · The Infinity Company
How to Choose an Electrician in India: Safety, Quotes and Hiring Checklist
Electrical work can affect the safety of a home or workplace, so choosing a qualified electrician should involve more than comparing prices. This guide explains how to describe the problem, evaluate relevant experience, compare written quotes, check safety practices and confirm the work before paying. Local licensing and inspection requirements vary, so verify the rules that apply to your location and job.
Quick answer: how do you choose a reliable electrician?

Confirm that the electrician has relevant experience for the job, explain the fault clearly, request a written estimate and ask how power will be isolated safely before work begins. For complex installations or regulated work, check applicable local requirements and credentials. Agree on materials, labour, testing, cleanup and warranty terms before authorising the work. Do not attempt dangerous electrical repairs yourself.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Identify the type and urgency of the electrical problem

Describe whether the issue involves a socket, light, circuit breaker, wiring, appliance connection, new installation or repeated power loss. If you notice smoke, burning smells, sparks, exposed live wires or a hot electrical panel, keep people away and contact the appropriate emergency or qualified electrical service. Do not touch damaged equipment or attempt to reset a repeatedly tripping breaker without understanding the cause.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Know when to stop using the circuit

If a circuit repeatedly trips, a socket becomes unusually hot or there is visible damage, stop using the affected equipment and seek qualified help. If it is safe to do so without approaching damaged equipment, isolate the supply using the appropriate switch; otherwise keep clear and contact the relevant emergency service or utility. Never work on live wiring or assume a fuse or breaker can be bypassed.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Check experience relevant to your job

Ask whether the electrician regularly handles the specific task, such as fault diagnosis, new circuits, lighting, earthing, distribution boards or commercial installations. A person experienced with simple replacements may not be suitable for a major rewiring project. For larger work, request a clear method, testing plan and details of any additional qualified professionals required.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Verify credentials and local requirements

Ask what training, licences, registrations or permits are required for the work in your location and how the electrician meets them. Requirements vary by jurisdiction and job type. For major installations or work requiring inspection, confirm who is responsible for approvals and certification. Do not treat an online profile, uniform or business card as proof of technical competence.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Request a site inspection for complex work

A reliable estimate often requires checking the affected circuit, load, wiring condition, access and safety risks. Explain the symptoms and share photographs only when they can be taken safely. Do not open panels or remove covers to take pictures. Ask whether the inspection fee is chargeable and whether it will be adjusted if you proceed with the work.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Get a written itemised estimate

Ask the provider to separate diagnosis, labour, materials, travel, emergency charges, testing and any applicable taxes. Clarify whether the price is fixed or an estimate and how extra work will be approved. For uncertain faults, ask what the initial diagnostic fee covers. Avoid agreeing to an open-ended job without a clear process for communicating changes and obtaining your consent.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Compare quotes on scope, not price alone

Two electricians may quote different amounts because they propose different materials, access methods, testing or repair scopes. Compare the same job description, parts specifications, exclusions, completion time and warranty. A very low quote may omit essential work; a high quote should still be explained. Ask for a revised like-for-like quote before choosing.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Ask about materials and replacement parts

Confirm the specifications, rating, brand or approved equivalent of important components such as switches, cables, protective devices and fittings. Ask whether the price includes the materials and whether unused parts will be returned. Use products appropriate for the circuit and local standards. Never accept a proposal to substitute underspecified parts merely to reduce the bill.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Understand electrical safety and protective devices

Ask the electrician to explain relevant earthing, overcurrent protection, residual-current protection where applicable, circuit loading and isolation procedures for the work. The correct solution depends on the installation and local code. Do not accept improvised bypasses or removal of protective devices to stop a circuit from tripping. Request that safety concerns be documented and resolved before the system is returned to service.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Plan access, timing and household safety

Agree on arrival time, estimated duration, areas that need access and whether power will be interrupted. Keep children and pets away from tools, open equipment and work zones. Tell the electrician about relevant access constraints and any vulnerable occupants who may depend on powered equipment. Confirm how the area will be left safe if work cannot be completed in one visit.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Ask how testing and handover will work

After the repair, ask what was changed and what tests were performed to confirm safe operation. For significant work, request relevant test results, certificates or documentation where required. Confirm that covers are refitted, circuits are labelled when appropriate and the work area is clean. Do not use equipment if the electrician reports that a safety issue remains unresolved.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Clarify workmanship warranty and call-backs

Ask what warranty applies to labour and supplied parts, how long it lasts, what it excludes and how to request a return visit. A warranty on a component may be different from a workmanship guarantee. Keep the estimate, invoice and communication. For recurring faults, document when the problem returns and share those details rather than repeatedly paying for unexplained temporary fixes.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Check reviews and references carefully

Look for specific feedback about diagnosis, communication, safety, punctuality and resolving problems. Recent reviews may be more relevant than a large overall rating, but reviews can be incomplete or manipulated. Where the job is substantial, ask for a relevant reference or examples of similar work with permission. Do not share private customer details or rely solely on a single online testimonial.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Confirm identity and protect property access

Before allowing entry, confirm the appointment and provider identity through the channel you used to book. Keep valuables and confidential papers secure and supervise access to sensitive areas. For commercial premises, follow your access-control procedures. Avoid paying an unknown person in advance for a large amount without a written scope, identity verification and a traceable payment record.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Understand payment terms and keep receipts

Agree when payment is due, whether a deposit is needed and which methods are accepted. For larger jobs, use staged payments linked to agreed milestones rather than paying the full amount before work begins. Ask for an invoice showing labour, materials and any applicable taxes. Keep proof of payment and do not pay additional charges that were not explained and approved.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Avoid common electrician hiring mistakes

Common mistakes include choosing solely by the lowest quote, ignoring repeated safety symptoms, approving work without a scope, accepting unspecified parts and failing to test the result. Another mistake is trying a DIY repair on a live circuit. Prioritise safety, insist on clear explanations and seek another qualified opinion if the diagnosis or price is not understandable.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Special considerations for landlords and tenants

Agree who is responsible for arranging and paying for the repair under the tenancy terms and applicable local rules. Document the issue, notify the responsible party and avoid making unauthorised changes to fixed wiring. In a rental property, keep the owner or property manager informed where required. If there is an immediate electrical hazard, keep people away and contact the appropriate responsible or emergency service promptly.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Special considerations for offices and shops

Commercial premises may have greater loads, three-phase equipment, emergency lighting, backup power or business continuity needs. Choose a provider with experience relevant to the installation and confirm any inspection, permit or shutdown requirements. Schedule work to reduce risk to staff and customers. Keep test records, invoices and updated circuit information in the business maintenance file.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
A simple checklist before booking

Describe the fault, check whether the situation is urgent, ask about relevant experience and applicable credentials, request a written estimate, confirm materials and testing, agree on timing and payment, and ask about warranty and documentation. Keep the contact details and job reference. If you see sparks, smoke or other serious hazards, prioritise safety over quote comparison.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Related local service guides

Read how to find reliable local service providers, how to compare home repair quotes and how to recognise local service scams. These guides help you compare scope, verify providers and reduce avoidable risks before booking.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Contact The Infinity Company

For general enquiries, contact The Infinity Company on WhatsApp at +91-7290007100 via this WhatsApp link. Never send sensitive identity or payment credentials to an unverified provider.
For any work involving electrical hazards, use a suitably qualified professional and follow the applicable local safety requirements. Keep the agreed scope and payment record for future reference.
Related reading: reliable local service providers, comparing home repair quotes and local service scam prevention.
Contact The Infinity Company on WhatsApp: +91-7290007100
Questions to ask during the first call

Ask what information the electrician needs to assess the job, whether a site visit is necessary, what the diagnostic fee covers and how urgent cases are prioritised. Explain the symptoms without guessing at the cause. Ask whether the provider can supply an itemised estimate and what would cause the price to change. For complex work, request the proposed testing and handover documentation in advance. Clear questions help both sides agree on the scope before work begins.
Keep the communication factual, retain the relevant records and prioritise safety over cost or convenience when a hazard may remain.
How to document the work for future maintenance

Keep the estimate, invoice, warranty details and a short description of what was repaired or installed. For larger work, request circuit labels, test records or updated drawings where appropriate. Record the date and provider contact details in a household or facilities maintenance file. These records can help a future electrician understand the installation and reduce repeat diagnosis. Store the documents securely without exposing private household information.
Keep the communication factual, retain the relevant records and prioritise safety over cost or convenience when a hazard may remain.
What to do if the repair fails or the quote changes

If the problem returns, stop using any equipment that appears unsafe and contact the provider with the original job reference and a factual description of the symptoms. Check the agreed warranty and ask what inspection or call-back is covered. If additional work is proposed, request an explanation and revised written estimate before approving it. For a serious safety concern or unresolved dispute, seek another suitably qualified opinion or use the relevant local complaint process.
Keep the communication factual, retain the relevant records and prioritise safety over cost or convenience when a hazard may remain.
How to Choose Website Hosting for a Small Business in India
Reliable website hosting supports your site’s availability, speed, security and ability to grow. The right choice depends on the type of website you run, the resources it needs, your team’s technical capacity and how quickly you must recover from a problem. This guide explains how small businesses in India can compare hosting options and plan a safe setup or migration.
Quick answer: how should a small business choose website hosting?

Choose hosting based on the website’s platform, expected traffic, reliability needs, support quality, backup and recovery options, security controls and total renewal cost. Start with a plan that meets real requirements and can scale when necessary. Do not choose only by introductory price or a headline speed claim. Check the provider’s service terms, resource limits and migration process before committing.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Identify what you are hosting

A simple brochure website, a WordPress business site, an online store and a custom web application have different resource and maintenance needs. List the platform, plugins or dependencies, expected traffic, storage, email needs, integrations and business-critical functions. If your application uses a database or background jobs, confirm that the hosting environment supports them. Match the plan to the actual architecture rather than choosing a product by name alone.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Understand common hosting types

Shared hosting places multiple websites on a common server environment and can suit smaller sites with modest needs. Managed WordPress hosting adds platform-specific maintenance or support features. VPS and cloud plans offer different levels of resource control and scalability, but may require more administration. Dedicated infrastructure can suit specialised workloads. Product labels differ by provider, so compare what is actually included.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Compare total cost, not just the first invoice

Check the initial term, renewal price, billing period, taxes, domain renewal, backups, email, SSL, migration, premium support and add-on charges. Introductory offers can make long-term costs difficult to compare. Ask what happens when storage or bandwidth limits are exceeded. Estimate the cost over a realistic period and record which services are optional versus necessary.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Review uptime commitments and service history

Read the provider’s uptime commitment, exclusions, incident communications and any service-credit process. A marketing claim is not the same as a clear service-level agreement. Ask how the provider handles maintenance windows and major outages. For a business-critical website, consider whether the business needs independent monitoring or a documented continuity plan. No hosting provider can promise that outages will never occur.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Check performance and resource limits

Compare the resources and constraints that affect your workload, such as CPU, memory, storage type, worker limits, database connections and concurrent requests. Ask whether traffic spikes trigger throttling or additional fees. Test the actual site after migration, including important pages, forms and checkout. A fast server helps, but application code, images, caching and third-party scripts also influence user experience.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Understand storage, bandwidth and visitor limits

Check storage type and capacity, file-count or inode limits, transfer allowances and any fair-use rules. Some plans advertise unmetered usage while still applying resource or acceptable-use restrictions. Estimate the size of your media library, backups, logs and database growth. Keep space for maintenance and recovery rather than allowing the account to operate permanently at its limit.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Evaluate backups and recovery options

Find out how often backups run, how long they are retained, what they include and how restoration works. Check whether backups are stored separately from the production account and whether restoring a single file or database is possible. Keep an independent backup of critical data and test recovery periodically. A backup that has never been restored is not a proven recovery plan.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Review security controls

Look for HTTPS support, account isolation, malware response, security updates, access logs, firewall options and protection against common attacks. Understand which controls are managed by the host and which remain your responsibility. Use unique passwords, multi-factor authentication and least-privilege access. No hosting package removes the need to update applications and secure administrator accounts.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Check SSL, domain and DNS management

Confirm how certificates are issued and renewed, whether custom domains and subdomains are supported and how DNS records are managed. Keep domain registration in a business-controlled account with current recovery details. Record important DNS settings before making changes. Avoid transferring domain ownership to an agency or contractor without a clear business reason and documented safeguards.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Assess support quality before you need it

Review support hours, available channels, response commitments, language options and whether help is included in the plan or billed separately. Ask how the provider handles urgent outages, account lockouts, malware incidents and migration problems. Read recent customer feedback carefully, distinguishing recurring operational issues from isolated complaints. Test a pre-sales question, but do not assume it guarantees the same experience during an incident.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Choose a data-centre region thoughtfully

Consider where your audience is located, the provider’s available regions, network performance, data-handling requirements and any contractual or regulatory obligations. A nearby server may help latency but is not the only factor in performance. Verify the actual hosting region and the locations used for backups or support where relevant. Do not make compliance claims based on a region label alone.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Check WordPress-specific requirements

For WordPress, confirm supported PHP and database versions, update policies, staging options, caching compatibility, plugin restrictions and restoration procedures. Ask how the host handles resource-heavy plugins, cron jobs and scheduled tasks. Keep WordPress core, themes and plugins updated and remove unused extensions. If a host manages updates, understand what it updates and whether changes are tested before production.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Plan migration before changing providers

List files, databases, DNS records, email, certificates, scheduled jobs, integrations and any custom configuration that must move. Create and test a full backup, set a migration window, reduce avoidable downtime and define a rollback plan. Test the migrated site through a temporary address or staging environment before switching DNS. Keep the old service available until critical functions have been verified.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Protect business email and deliverability

If email is bundled with hosting, check mailbox limits, retention, spam filtering, backup and support. Confirm that the domain can use the required DNS records for mail authentication, including SPF, DKIM and DMARC where applicable. Avoid changing mail-related DNS records without understanding their effect. For business-critical email, compare a dedicated email service with the hosting provider’s included mailbox offering.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Test staging and deployment workflows

A staging environment can help you test plugin updates, design changes and new functionality before visitors see them. Check whether staging copies can contain real customer data and how access is protected. Use a documented release process, review forms and payment paths after changes, and keep a way to roll back failed updates. Staging availability and limits vary by provider.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Plan for traffic growth and scaling

Estimate likely growth and identify what would trigger an upgrade: sustained resource usage, slower responses, errors or new application requirements. Check whether scaling requires downtime, a plan migration or manual server work. Do not pay for expensive capacity far beyond your current needs without a clear reason. Keep performance monitoring and application optimisation in the plan as traffic grows.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Understand compliance and customer-data responsibilities

Determine what personal or business data your website collects and where it is stored, processed and backed up. Review the host’s privacy terms, security responsibilities, subprocessors and incident-notification provisions. Hosting alone does not make a business compliant. Apply appropriate data minimisation, access controls and retention practices, and seek qualified advice where your sector or data creates additional obligations.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Measure real website performance after setup

Monitor page load behaviour, server response, uptime, errors, form completion and important customer journeys. Use suitable real-user and synthetic monitoring rather than relying on one test run. Test from locations and devices relevant to your audience. Establish a baseline before changing caching, CDN or server settings so you can tell whether a change helped.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Create a practical hosting comparison sheet

For each shortlisted plan, record renewal price, resource limits, backup retention, restoration process, security responsibilities, support availability, staging, migration support, email features and cancellation terms. Mark any requirement that is unclear and ask the provider for a written answer. Compare the same set of needs across providers instead of relying on marketing labels or isolated benchmark claims.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Avoid common hosting mistakes

Common mistakes include choosing on price alone, failing to maintain independent backups, sharing the owner login, ignoring renewal charges, overlooking email DNS and moving a live site without a rollback plan. Another risk is assuming that a managed service handles every security or application task. Write down which party owns each responsibility and review the arrangement when the site changes.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
A 30-day hosting setup and review plan

Week 1: document the website’s requirements, traffic, data and critical functions. Week 2: compare providers and confirm costs, support, backups and security terms. Week 3: prepare the site, migrate in a controlled way and test key journeys. Week 4: monitor performance, test a restore or confirm the recovery process, review access permissions and document support contacts. Adjust the schedule to the site’s complexity.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Hosting readiness checklist

Before purchase or migration, confirm platform compatibility, renewal pricing, resource limits, backup retention, recovery steps, HTTPS, support, DNS control, email requirements and cancellation terms. After launch, test forms and checkout, check logs, verify certificates, monitor errors and secure administrator accounts. Keep records of the provider, plan, renewal date and escalation route in a business-controlled location.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Related technology guides

Continue with our business website maintenance checklist, cloud storage for small businesses and small-business cybersecurity. These resources help connect hosting decisions with ongoing maintenance, data recovery and account security.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Contact The Infinity Company

For general enquiries, contact The Infinity Company on WhatsApp at +91-7290007100 using this WhatsApp link. Before giving a provider or agency access, verify the scope and keep domain ownership, billing access and recovery details under your business’s control.
Verify current plan terms and responsibilities with the provider before making a purchase or changing a live site. Keep records of configuration changes and test critical customer journeys after each major change.
Related reading: website maintenance, cloud storage and cybersecurity for small businesses.